
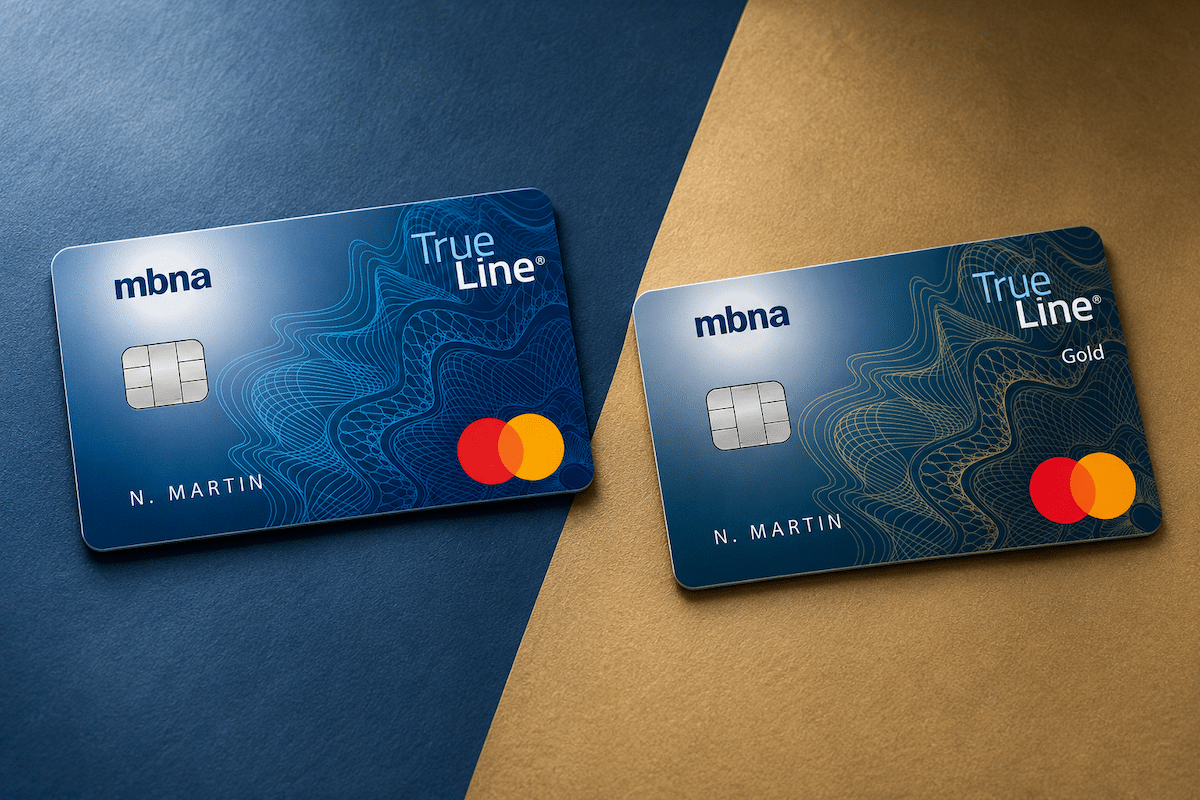
Here at Frugal Flyer, we’ve been fans of MBNA credit cards for a while. Their portfolio of cards includes products that help Canadians build credit while not getting hit by crazy interest rates. They also routinely offer balance transfers, which allow you to borrow large amounts of money at 0% interest. These can be leveraged to consolidate debt or build wealth.
In an era of rising fiscal uncertainty, it’s good to know which MBNA product is the best for your needs if you are looking to add a new card to your wallet. Let’s get into the details and comparison of the MBNA True Line Mastercard vs. the MBNA True Line Gold Mastercard to determine which is best.
What’s the Advantage of the MBNA True Line Mastercard?
Let’s start by talking about the MBNA True Line Mastercard.
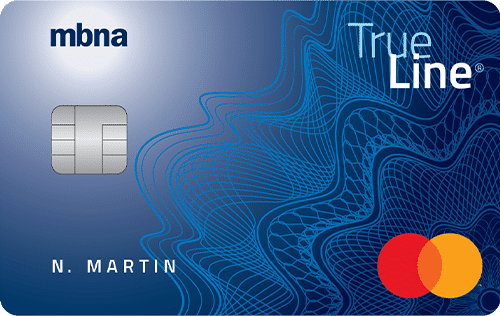
The MBNA True Line® Mastercard® offers a 0% promotional annual interest rate for 12 months on balance transfers completed within 90 days of account opening.
Earn when you apply through Frugal Flyer.
None
$0
$50+
$0
Yes
–
This product is unique in the Canadian market because it has no annual fee and a low interest rate on new purchases of only 12.99%. Even its regular rate for balance transfers is 17.99%, though its cash advance rate remains the customary 24.99%.
However, the real reason this is a favourite in the personal finance space is that it often has 0% interest balance transfer promos as a welcome bonus that charge only between 1-3% of the amount borrowed. So, for example, receiving access to $10,000 for 12 months for a total cost of $300, or sometimes as low as $100, is a great deal if you need to lump debt together or want to invest intelligently.
Of course, it’s necessary to keep an eye on how much you’re borrowing so as to not adversely affect your credit score, but overall the MBNA True Line Mastercard is a great addition to any wallet that wants to leverage the magic of balance transfers.
MBNA True Line Gold Mastercard: Like a Line of Credit
On the other hand, the MBNA True Line Gold Mastercard charges only 10.99% interest on new purchases, as well as 13.99% on balance transfers and the customary 24.99% on cash advances, albeit at the cost of a $39 annual fee.
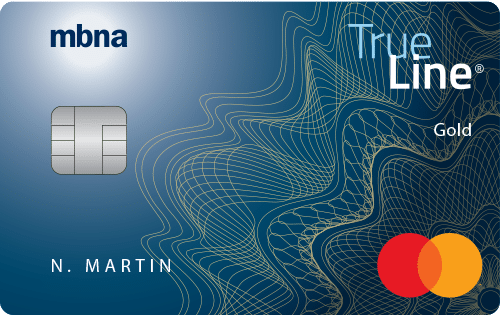
The MBNA True Line® Gold Mastercard® is the lowest interest rate MBNA credit card, offering a 10.99% standard interest rate on purchases.
None
$0
$0+
$39
Yes
–
This purchase interest rate is one of the lowest in Canada, as many commercial lines of credit, even for prime borrowers, are often north of 8.5% these days. We don’t advise carrying a balance here at Frugal Flyer, but sometimes, life has needs, and it’s not always easy to get approved for a line of credit anymore.
The balance transfer rate of only 13.99% is also not terrible because it means if you get a 0% introductory offer and can’t pay off a balance transfer in time, you won’t be on the hook for punishing higher levels of interest.
Now, remember: a line of credit does let you take out money. This can only be used for products or services you can normally purchase with a credit card, so don’t try to use your MBNA True Line Gold Mastercard to finance a new vehicle. However, it does remain a competitive way to keep the cost of borrowing down on other items.
The Verdict: Which True Line Mastercard Is Best?
Overall, we can recommend the no-fee MBNA True Line Mastercard for most cases. We definitely encourage using balance transfers for their intended purpose, which is consolidating high-interest debt into less painful debt, or using debt to invest wisely.
Credit is an amazing tool available to Canadians far more freely than it is to citizens of other parts of the world, so we invite you to use the great products that are available in a fiscally prudent fashion.
Kirin Tsang
Latest posts by Kirin Tsang (see all)
- Blue Rewards & VIPorter: A New Partnership With Transferable Points Coming Soon - Nov 13, 2026
- Canadian Capital One Quicksilver Cards: How Do They Measure Up? - Nov 10, 2026
- MBNA True Line vs. MBNA True Line Gold: Which Is Best? - Nov 3, 2026
- How to Get Free Roadside Assistance: Ditch CAA & Sign Up for These Credit Cards - Oct 30, 2026
- All of Accor Live Limitless’ Hotel Brands Explained - Oct 26, 2026
