
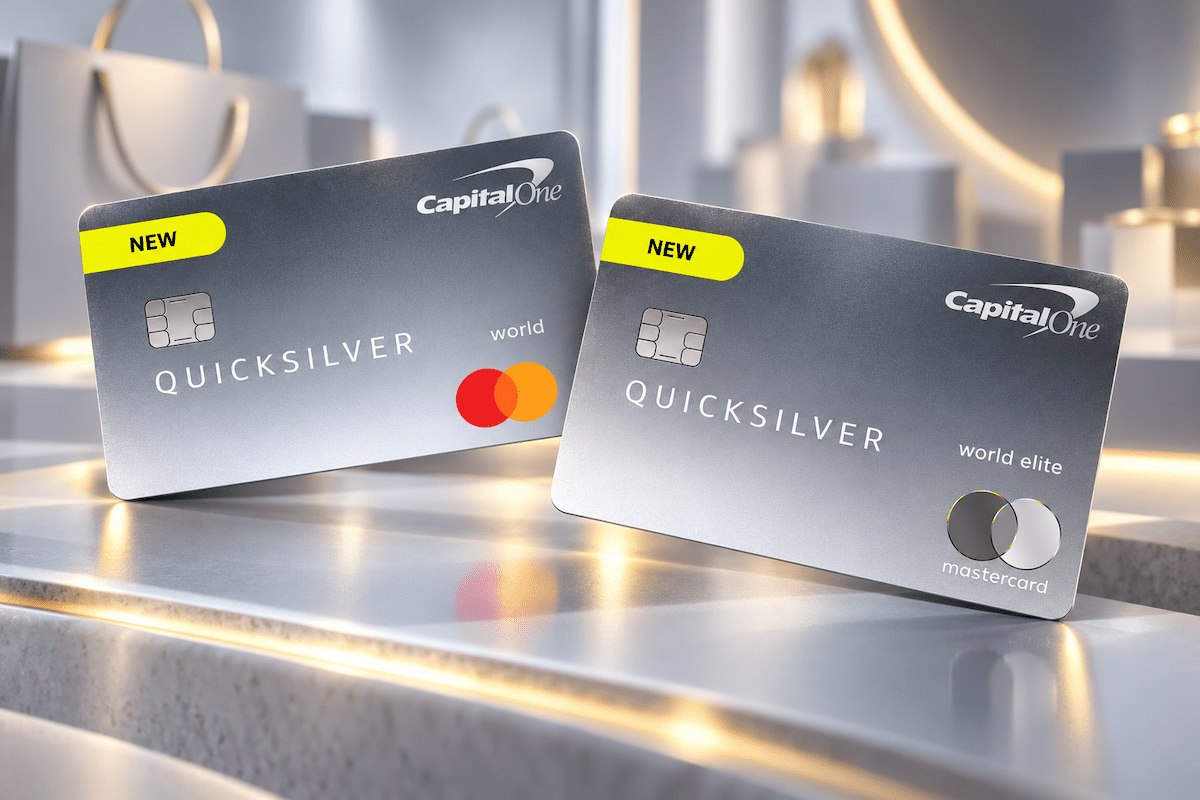
Wait a second, is Capital One still operating in Canada? You may be surprised to find out that yes, they are, though primarily as the “lender of last resort” with a bevvy of credit-builder products for young folks or those recovering from financial difficulties.
This has been the brand for the past couple of years. It’s refreshing, therefore, to see Capital One rejuvenate its portfolio with the brand new (as of October 2026) Quicksilver Mastercards. These new products feature no annual fee, no foreign transaction fees, and uncapped 3% back on groceries and gas.
Let’s dig into the details and look at how they hold up against the best cash back credit cards in Canada.
What are the Capital One Quicksilver Cards?
There are two: the Capital One Quicksilver World Elite Mastercard and the Capital One Quicksilver World Mastercard.
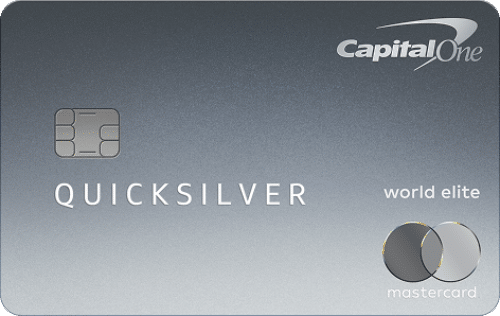
The Capital One Quicksilver World Elite Mastercard offers a rare combination of premium benefits for a $0 annual fee, featuring an unlimited first-year cash-back match of up to 6% and no foreign transaction fees.
2x cash back
$0
$0+
$0
No
–

The Capital One Quicksilver World Mastercard offers a rare combination of premium benefits for a $0 annual fee, featuring an unlimited first-year cash-back match of up to 6% and no foreign transaction fees.
2x cash back
$0
$0+
$0
No
–
Both cards earn 3% cash back at grocery stores, 3% at gas stations and EV charging stations, and 1% on everything else. One of the best parts of both cards is that they feature no spending caps, meaning you will always earn the maximum cash back no matter how much you spend in a year.
These new offerings are probably designed to help Capital One win back prime borrowers, folks with higher incomes and more established credit ratings. That’s why both of these have different income requirements: the World Elite needs the typical $80,000 personal or $150,000 minimum household income, whereas the World version requires $50,000 in personal or $80,000 in minimum household income.
Oddly, the higher credit card tier has the lower interest rate (20.9% against 21.9% to 29.9%), though you should strive to never pay a cent in interest, so don’t let that affect your choice of card.
At the time of writing, the Capital One Quicksilver Mastercards don’t have a traditional welcome bonus. Instead, they will double every dollar of cash back new cardholders earn in their first 365 days with no limit.
This works out to 6% on groceries and gas and 2% back on everything else. The catch is that the bonus is paid as a lump sum after the year ends, so you’ll need to wait about 13 months. On the other hand, you can redeem your regularly earned cashback as a statement credit at any time on the website or via the app. There’s no minimum, though be advised it does not count against your minimum payment.
Now for the fine print: the grocery category runs on merchant category codes that exclude “superstores like Walmart and Costco,” so your Costco or Wholesale Club purchases net 1%.
These cards also offer insurance covering flight delays, baggage, price protection, and rental cars for up to 31 days, but not travel medical or airport lounge access.
What Makes The Capital One Quicksilver Cards an Interesting New Option for Canadians
Let’s be real: no-fee credit cards usually give you mediocre rates and even more underwhelming maximum spend caps. Earning an uncapped 3% on two of Canadians’ biggest household categories is rare, and unlikely to last indefinitely if we’re being honest. Better yet, these rates apply around the world, so if you’re buying groceries on holiday, it should still code properly.
However, what’s even better about these products is that they don’t charge any foreign exchange fees. Most Canadian cards add 2.5% to every foreign currency purchase, and the cards that waive foreign transaction fees mostly charge a silver dollar or more for it.
For example, it costs $120 a year for the Scotiabank Gold American Express Card and $150 for the Scotiabank Passport Visa Infinite + Card. Both of these cards are excellent, but they’re not free.
As for no-fee options, there’s one, count it one, other option in the entirety of Canada: the Home Trust Preferred Visa Card. This card earns 1% cashback in Canada and 0% on foreign transactions, and your cashback is a statement credit once a year in January. This card is competitive but nowhere near as competitive as the new Quicksilvers.
There’s also Rogers Red World Elite Mastercard and Rogers Red Mastercard in this category, but unfortunately they charge 2.5% FX and provide 3% and 2% cashback on US dollar purchases only.
How the Capital One Quicksilver Cards Measure Up Against Top Cashback Cards in Canada
The Frugal Flyer team has finished a little accounting exercise to see how the new Capital One Quicksilver cards compare against the best cashback cards in Canada.
For the math, picture two parents splitting a $3,000 monthly budget, each putting $1,500 on their own card: $400 on groceries, $150 each on gas, recurring bills, and dining, $50 on transit, and $600 on everything else. The table shows a year of cash back minus the annual fee at that level, then again if one card carried the full $3,000.
| Credit Card | Annual Fee | Groceries / Gas | Spending Bonus Cap | Annual Net at $1,500 Monthly Spend (See breakdown above) | Annual Net at $3,000 Monthly Spend (See breakdown above) |
|---|---|---|---|---|---|
| Capital One Quicksilver World & World Elite | $0 | 3% / 3% | None | $312 | $624 |
| Scotia Momentum Visa Infinite + Card | $120 | 4% / 2% | $25,000 a year | $282 | $684 |
| BMO CashBack World Elite Mastercard | $139 | 5% / 3% | $500 / $300 per statement | $305 | $605 |
| Neo World Elite Mastercard | $149 | 5% / 3% | $1,000 each per month | $313 | $775 |
| TD Cash Back Visa Infinite Card | $139 | 3% / 3% | $15,000 a year per category | $221 | $581 |
| CIBC Dividend Visa Infinite Card | $120 | 4% / 4% | $20,000 a year combined | $300 | $684 |
| Rogers Red World Elite Mastercard | $0 | 1.5% to 2% | $61,000 a year | $270 to $360 | $540 to $720 |
| Tangerine Money-Back World Mastercard | $0 | 2% if selected as bonus category | None | $216 | $432 |
| Simplii Cash Back Visa | $0 | 1.5% / 1.5% | $15,000 a year | $237 | $456 |
| Scotia Momentum No-Fee Visa | $0 | 1% / 1% | $15,000 a year | $135 | $255 |
At $1,500 a month, the free Capital One Quicksilver card of any tier is in a dead heat with Neo for the lead. Only Rogers customers using the Rogers Red family of cards do any better.
On the other hand, an annual fee is only one cost. While it’s often better to unlock the power of two-player mode, it’s important to look at what happens if you spend more on one card while paying the same annual fee.
When spending more than $1,500 a month, the Neo World Elite Mastercard tends to overtake the Quicksilver quickly. On the other hand, it takes until about $1,700 monthly for the CIBC Cashback Visa Infinite, and the Scotia Momentum Visa Infinite + Card wins out at $2,000.
However, we would be remiss to tell you that all cards are the same. Not all people have the same expenses.
For those with large recurring bill payments, the Scotia Momentum Visa Infinite + Card is a clear winner. It pays 4% on groceries and recurring bills, where Quicksilver pays 3% and 1%, though its 2% on gas is a point worse. It also has stronger travel medical and mobile device insurance, though it does have an annual fee. Still, in the era of high monthly subscriptions, this is a superior choice if you’re paying for a recurring gym membership and Anthropic big bundles.
The Scotia Momentum Visa Infinite + Card earns 4% cash back on grocery purchases, eligible recurring bill payments, and subscription purchases.
Earn when you apply through Frugal Flyer.
$200 cash back
$2,000
$350+
$120 (FYF)
Yes
Apr 30, 2027
Similarly, the BMO CashBack World Elite Mastercard is the city commuter’s choice. For people who take a lot of Uber, it nets 4% on transit (including rideshare) and 5% on your first $500 of groceries each statement. This means that it’s a much better choice for, say, those living in Toronto taking the GO train every day but not buying gas.
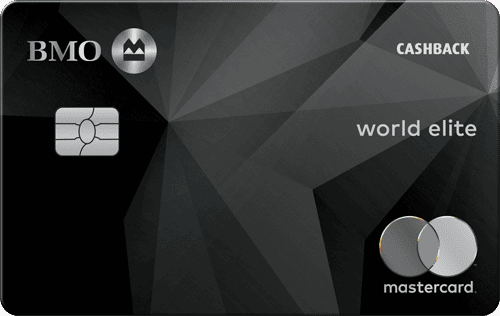

The BMO CashBack® World Elite®* Mastercard®* earns up to 5% cash back on grocery purchases, plus elevated cash back earning rates on other popular spending categories.*
Earn when you apply through Frugal Flyer.
$480 cash back
$24,000
$605+
$139 (FYF)
Yes
Oct 31, 2027
The Neo World Elite Mastercard is the grocery heavyweight. Its 5% is eligible for up to $1,000 of groceries a month, and it adds 4% on recurring bills, so it scales better than anything here. Especially if you are enough of a masochist to shop at Whole Foods.
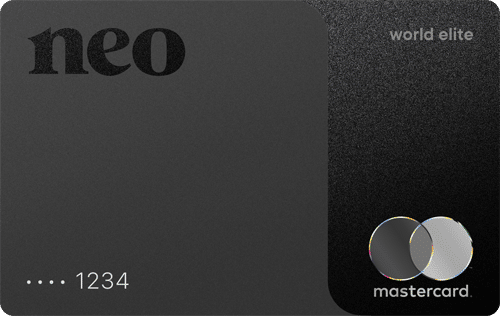

The Neo World Elite Mastercard is one of the best cash back cards in Canada, offering a generous 5% cash back on groceries, 4% on recurring bills, and 3% on gas purchases.
Earn when you apply through Frugal Flyer.
None
$0
$60+
$149 (FYF)
Yes
–
The TD Cash Back Visa Infinite Card ties Quicksilver at 3% on groceries and gas, and only pulls ahead with its 3% on transit, recurring bills, and streaming. It’s not a terrible value at $139 per year; it’s a winner if you bank with TD and have an eligible chequing account for a fee waiver.
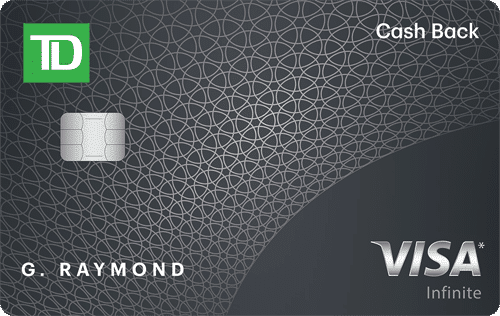
The TD Cash Back Visa Infinite* Card earns 3% cash back on all eligible grocery purchases, gas purchases, and regularly recurring bill payments.
$350 cash back
$3,500
$350+
$139 (FYF)
Yes
–
The CIBC Dividend Visa Infinite Card is the pick for EV drivers as its 4% applies to both gas and EV charging, alongside 4% on groceries and 2% on dining, transportation, and recurring bills. Its bonus rates stop after $20,000 a year per category. That means it can only earn $80 a year on each of those categories versus an unlimited 3% for the Quicksilver. If you are charging three Teslas a day, it’s probably the better choice.
The CIBC Dividend Visa Infinite card earns cash back and gives cardholders the opportunity to earn 4% cash back on gas and grocery purchases.
$250 cash back
$2,000
$250+
$120 (FYF)
Yes
–
The no-fee cards are a bit easier to understand. The Rogers Red World Elite Mastercard pays a flat 1.5%, or 2% for Rogers, Fido, Shaw, and Comwave customers, which means groceries and gas would have to be 50% of your spending to be more efficient than the Quicksilver.

With the Rogers Red World Elite® Mastercard, Rogers, Fido, Shaw, and Comwave postpaid consumer customers can earn 2% cash back on all eligible purchases.
Earn when you apply through Frugal Flyer.
None
$0
$50+
$0
Yes
–
On the other hand, the Tangerine Money-Back World Mastercard lets you pick up to three 2% categories and pays 0.5% on everything else. It’s probably the closest equivalent to the Quicksilver, though its 1% on everything else edges out the venerable Tangerine.


The Tangerine Money-Back World Mastercard offers cardholders the ability to choose up to three accelerated spending categories to increase their cash back earnings.
Earn when you apply through Frugal Flyer.
$120 cash back
$1,500
$195+
$0
Yes
Nov 30, 2026
The Simplii Financial Cash Back Visa Card offers 4% on restaurants, which is worth keeping it around for, but it’s capped at $5,000 in spend (or $200 in rewards) a year, and its 1.5% on groceries and gas is half of Quicksilver’s, so probably not better.
The Simplii Financial Cash Back Visa card earns 4% cash back on purchases at restaurants, bars, and coffee shops on up to $5,000 in spending per calendar year.
Earn when you apply through Frugal Flyer.
$80 cash back
$1,000
$140+
$0
Yes
–
Finally, the Scotia Momentum No-Fee Visa Card tops out at 1%, which Quicksilver matches or beats on every level.
What’s Next for Capital One Canada?
Historically, Capital One Canada has been focused on subprime lending and credit-building products. However, the launch of the Quicksilver Mastercards indicates Capital One is willing to make one of the most innovative new products on the market to win back prime borrowers.
3% flat, uncapped, on groceries and gas may not be the first choice for ruthless Miles & Points maximalists, but it’s a fantastic, easy-to-understand rewards program for normal people. In an era of a weakening Canadian dollar and uncertainty on overseas trade, waiving the 2.5% customary FX fee and granting 1% cashback earning on all transactions is a remarkable act of goodwill.
Enthusiasts still mourn the loss of the old Canadian Capital One Aspire Travel World Elite, but this re-launch of rewards credit cards by Capital One in Canada is something hopeful to look forward to.
Conclusion
While the Quicksilver cards won’t immediately dethrone all their competition, it’s still an excellent entrant. For the average Canadian who wants cash back and doesn’t want to pay FX fees, these products are about as easy a recommendation as can be.
It’s never a bad time to have more innovative competition on the personal finance product market, and I hope we see more interesting products coming from Capital One Canada in the near future.
Kirin Tsang
Latest posts by Kirin Tsang (see all)
- Canadian Capital One Quicksilver Cards: How Do They Measure Up? - Nov 10, 2026
- How to Get Free Roadside Assistance: Ditch CAA & Sign Up for These Credit Cards - Oct 30, 2026
- All of Accor Live Limitless’ Hotel Brands Explained - Oct 26, 2026
- Canada Post MyMail: Track Your Incoming Credit Card Mail & More - Oct 12, 2026
- Scotiabank Amex Offers: Don’t Leave Cash On The Table - Oct 5, 2026
