As any points and miles enthusiast knows, maximizing every dollar spent is key to earning as many rewards as possible through responsible credit card use. For many people, rent and housing costs make up their largest monthly expense, making them an obvious opportunity to earn more rewards.
Rent payment services like Chexy have made it possible to earn credit card rewards on one of our largest recurring expenses for some time. However, mortgage payments were one of the last major expenses where earning rewards was difficult.
Chexy has recently launched Canada’s first mortgage payment rewards program, allowing members to earn Air Canada Aeroplan points and Status Qualifying Credit (SQC) on eligible mortgage payments for a fixed fee.
Let’s take a closer look at how Chexy Mortgages works and whether paying your mortgage through Chexy is worth it.
What Are Chexy Mortgage Payments?
The normal Chexy process for paying rent, bills, utilities, and taxes with a credit card is fairly straightforward. You set up a one-time or recurring payment, and Chexy charges your credit card and forwards the payment to the biller on your behalf for a 1.75% processing fee.
However, mortgage lenders generally don’t want borrowers paying their mortgage with a credit card, likely due to lender compliance requirements, Chexy doesn’t involve any credit card transactions when processing mortgage payments.
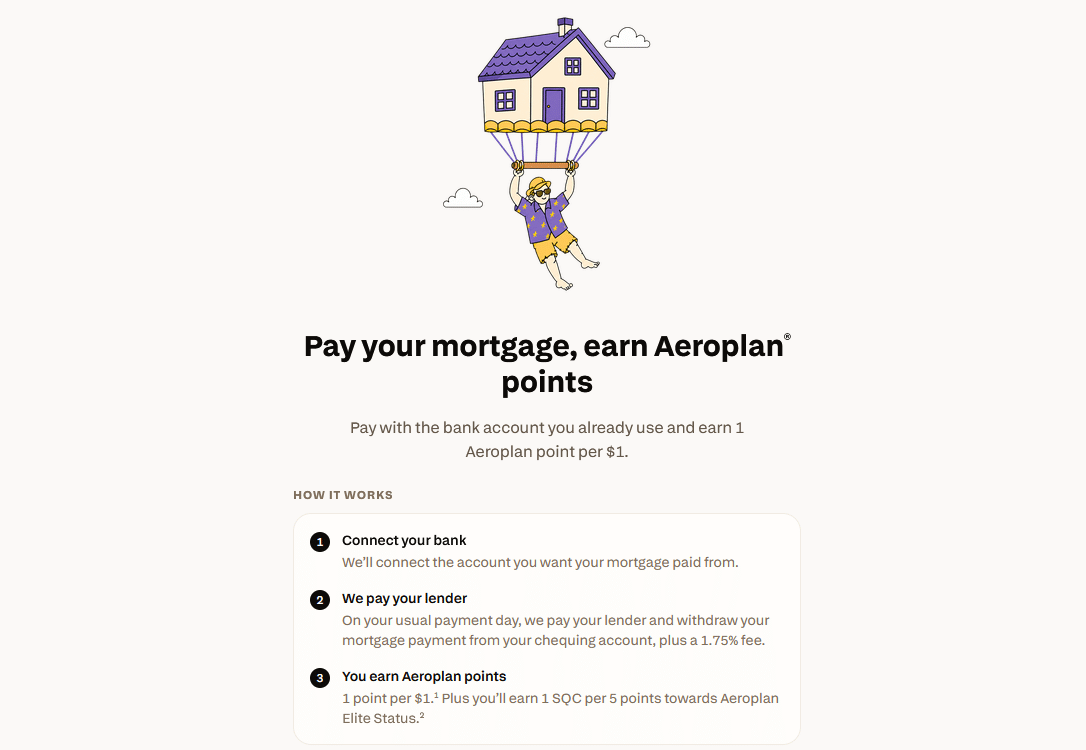
Instead, Chexy acts as an intermediary by making the mortgage payment on your behalf and withdrawing the equivalent amount plus a 1.75% processing fee from your chequing account. In return, you earn Aeroplan points and Status Qualifying Credits (SQC) on each payment.
This service works with any Canadian mortgage provider and only requires you to update the bank account used for your mortgage payments with your lender. If you want to use the service, you don’t have to refinance, change lenders, or switch banks. Your mortgage terms won’t change, and your payment date will stay the same.
| Feature | Chexy Mortgage Payments |
|---|---|
| Aeroplan Earn Rate | 1 point per $1 |
| SQC Earn Rate | 1 SQC per 5 Aeroplan points (max 25,000 SQC per calendar year) |
| Processing Fee | 1.75% |
| Payment Method | Chequing account / eligible debit |
| Eligible Lenders | Canadian residential mortgage lenders |
| Aeroplan Points Cap | None |
A couple of details are worth noting. Status Qualifying Credits (SQC) earned through Chexy fall under the Everyday Partners category, which caps earnings at 25,000 SQC per calendar year across the category, not just through Chexy.
Additionally, Aeroplan points are earned only on the mortgage payment amount. The Chexy processing fee is not eligible to earn Aeroplan points.
How to Earn Aeroplan Points on Mortgage Payments with Chexy
To set up your mortgage payments through Chexy, you’ll need to complete a few steps on the Chexy website, including connecting your chequing account and mortgage lender, then entering your mortgage payment amount and frequency.
The first step is to confirm that Chexy supports your mortgage lender. Chexy works with most Canadian mortgage providers, including the major banks, regional credit unions, and private lenders.
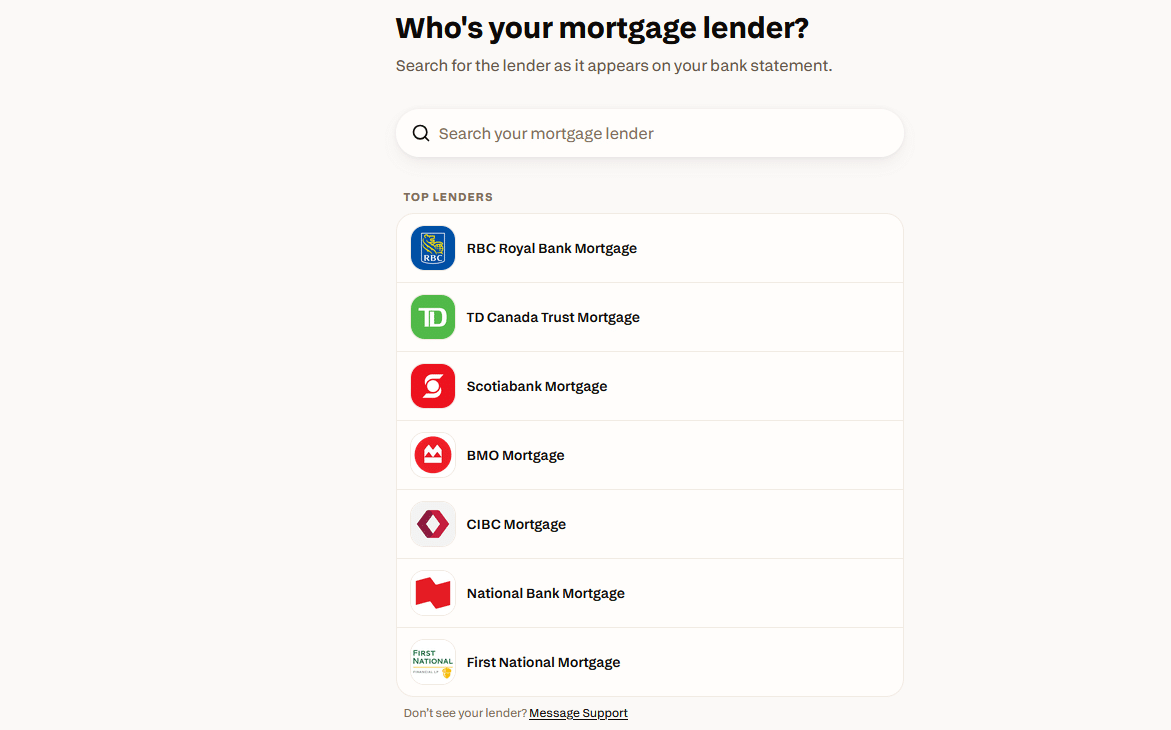
Next, you’ll need to connect your chequing account from which Chexy will withdrawal your mortgage payment.
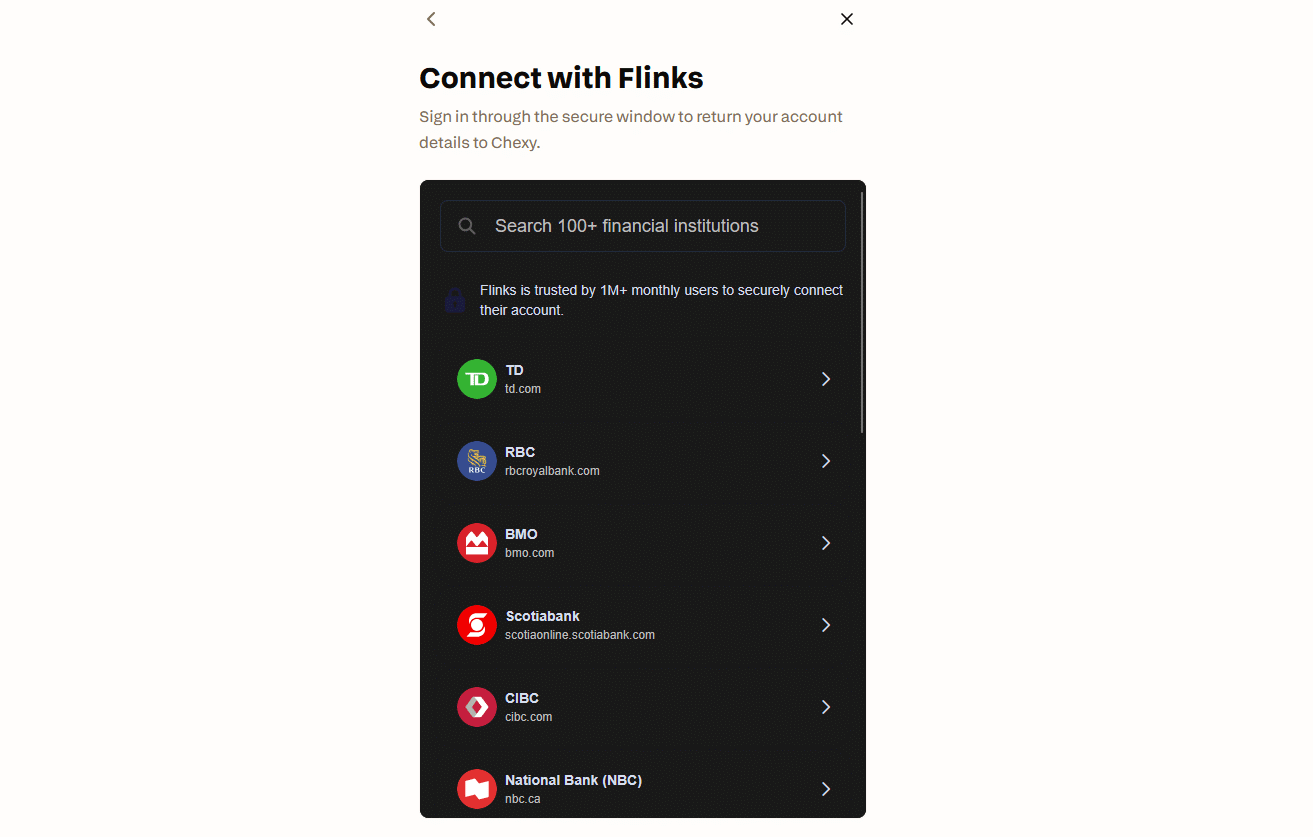
Once setup is complete, enter your mortgage payment amount and frequency, then schedule your first payment. Future payments will be processed automatically according to your selected schedule.
Chexy will also provide unique account details (account number, transit number, institution) that you’ll need to update with your mortgage lender to have payments withdrawn from Chexy.
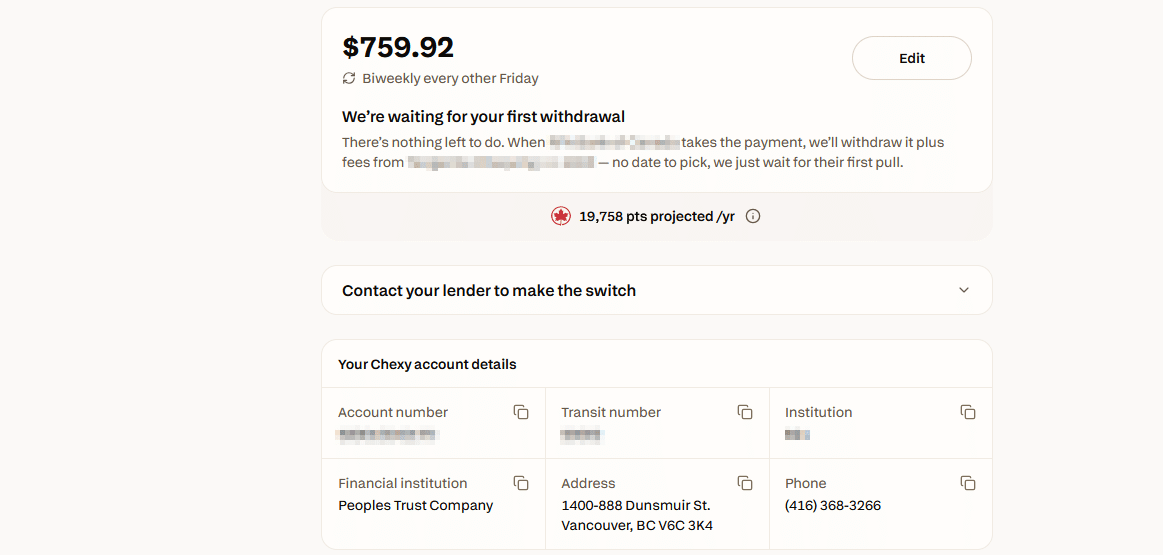
Depending on your mortgage lender, you may be able to update your banking information online. Otherwise, you may need to submit a form with your Chexy account details and a void cheque, which Chexy provides. Once the update is complete, your mortgage payments should continue as usual without any further action required.
How Many Aeroplan Points Can You Earn?
Mortgage payments processed through Chexy earn 1 Aeroplan point per $1 paid toward the mortgage, excluding the processing fee. There is no annual cap on the number of Aeroplan points you can earn.
| Monthly Mortgage | Annual Payments | Aeroplan Points |
|---|---|---|
| $1,500 | $18,000 | 18,000 |
| $2,500 | $30,000 | 30,000 |
| $3,500 | $42,000 | 42,000 |
| $5,000 | $60,000 | 60,000 |
| $10,416.67 | $125,000 | 125,000 |
Given the earn rate, you’re unlikely to rack up many Aeroplan points, especially since they accumulate slowly throughout the year rather than in a meaningful lump sum. At best, paying a mortgage with Chexy can be described as a monthly Aeroplan points subscription. And unless you have an abnormally large mortgage, the annual points haul is unlikely to amount to much.
Earn Aeroplan Status Qualifying Credits (SQC) on Mortgage Payments
Perhaps the most interesting aspect of using Chexy for your mortgage is the opportunity to earn SQC on top of Aeroplan points.
Status Qualifying Credits (SQC) determine your Aeroplan Elite Status level with Air Canada. The first tier, Aeroplan 25K, requires earning 25,000 SQC in a calendar year. This is also the maximum number of SQC you can earn through the Everyday Partners category, including Chexy. In other words, you can earn Aeroplan 25K Status for the remainder of the current year and the following year without taking a single flight.
This 25,000 SQC can also go a long way to pushing you over a threshold toward one of the higher Air Canada status levels.
Status Qualifying Credits (SQC) are earned at a rate of 1 SQC per 5 Aeroplan points.
| Monthly Mortgage | Annual Payments | Status Qualifying Credits (SQC) |
|---|---|---|
| $1,500 | $18,000 | 3,600 |
| $2,500 | $30,000 | 6,000 |
| $3,500 | $42,000 | 8,400 |
| $5,000 | $60,000 | 12,000 |
| $10,416.67 | $125,000 | 25,000 |
For users of the program that care about earning status or advancing their status level, this is one of the most effective methods to earn a large amount of SQC. While the Aeroplan points earned are a consideration, the ability to earn SQC in addition is likely to be the most appealing aspect of the program and deciding factor of whether to use the service.
Chexy Mortgage Payment Fees
Chexy charges a 1.75% processing fee on all mortgage payments, the same fee applied to credit card payments.
At an earning rate of one Aeroplan point per dollar spent, the 1.75% fee means you’re effectively buying Aeroplan points at a rate of 1.75 cents per point. This is your break-even point, meaning you need to get at least 1.75 cents in value from each point to offset the processing fee.
We value Aeroplan points at 2.0 cents per point (CAD), as a result of the program’s extensive partner network and opportunities to book high-value business and first class flights.
However, your actual value may be lower if you primarily redeem points for economy flights within North America or book flights with high dynamic award pricing. In these cases, a valuation closer to 1.5 cents per point may be more realistic, making it harder to justify the processing fee.
The table below outlines common mortgage payment amounts and their associated Chexy fees, along with the monthly payment required to maximize SQC earnings through Chexy.
| Monthly Mortgage | Monthly Fee | Annual Fee |
|---|---|---|
| $1,500 | $26.25 | $315 |
| $2,500 | $43.75 | $525 |
| $3,500 | $61.25 | $735 |
| $5,000 | $87.50 | $1,050 |
| $10,416.67 | $182.29 | $2,187.50 |
For example, if you value Aeroplan points at 2.0 cents each and have a monthly mortgage payment of $2,500, you would earn 30,000 Aeroplan points over the course of a year while paying $525 in processing fees. This would result in a net positive value of $75.
That’s hardly a game-changing return for an entire year of mortgage payments. However, if you consistently redeem Aeroplan points for high-value business class flights on partner airlines, the numbers become more favorable.
On the other hand, casual travelers who typically redeem Aeroplan points for economy flights within North America may struggle to get more than 1.5 cents per point from their redemptions. At that valuation, the cost of earning points through Chexy outweighs their value, making it difficult to justify the strategy on points alone.
Another factor to consider is Chexy Plus, which reduces the transaction fee on mortgage payments to 1.5% for annual subscribers. I won’t go into detail here, as I’ve already published a full breakdown of the program’s costs and benefits.
In short, if you process a large volume of payments through Chexy, the $80,000 in annual spending break-even point for Chexy Plus would bring the acquisition cost down to 1.5 cents per point and further improve the value proposition of earning Aeroplan points through Chexy.
Is Paying Your Mortgage with Chexy Worth It?
When it comes to buying points or paying for a subscription that earns points gradually rather than in a lump sum, the answer is rarely a simple yes or no. So, it depends.
If you don’t care about Air Canada status, you’re just buying Aeroplan points at 1.75 cents each. Granted, this is cheaper than buying points directly from Air Canada, but there are an almost limitless number of ways to earn Aeroplan points for less in Canada, including credit card welcome bonuses, transfers from partner programs, and shopping through the Aeroplan eStore, just to name a few. Unless you’ve exhausted those options, paying your mortgage through Chexy for the specific purpose of earning Aeroplan points probably isn’t worth it.
However, the calculation changes significantly if you value Air Canada status and fly enough to take advantage of its benefits.
I don’t think most people considering Chexy will have a monthly mortgage payment of more than $10,000, which would be required to earn the maximum 25,000 SQC through Chexy. Instead, I think the more realistic use case is earning SQC to bridge a smaller gap to the next status tier.
For example, suppose you’re a regular Air Canada flyer who earns 45,000 SQC organically. Using Chexy to earn the additional 5,000 SQC needed to reach Air Canada 50K status could be well worth it.
Earning 5,000 SQC through Chexy would require $25,000 in mortgage payments over the course of a year. With the 1.75% processing fee, you’d pay $437.50 in fees. Assuming a conservative Aeroplan point valuation of 1.5 cents per point, the points earned on those mortgage payments would be worth $375.
That leaves an effective cost of just $62.50 to earn the additional 5,000 SQC and reach 50K status. Given the range of benefits that come with Air Canada 50K status, I think most frequent flyers would agree that paying $62.50 to unlock those benefits is an excellent deal.
Ultimately, you’ll need to consider how much you value Air Canada status, how much SQC you expect to earn organically, and whether earning SQC through Chexy will be enough to push you to the next status tier.
A final factor to consider is the opportunity cost of paying processing fees on top of your monthly mortgage payment to earn a currency that is subject to constant devaluation, as all miles and points are.
Rather than paying Chexy fees, you could put that money toward paying down the principal on your mortgage, potentially shaving years off your mortgage term and saving thousands of dollars in interest payments. Those savings could easily outweigh the value of any Aeroplan points earned, especially when there are plenty of other ways to earn Aeroplan points in Canada without paying additional fees.
Conclusion
At the end of the day, paying your mortgage through Chexy is essentially a monthly Aeroplan points subscription. As with any points-buying strategy or subscription, its value depends on your individual circumstances and how you redeem your Aeroplan points.
For casual Aeroplan users, paying your mortgage through Chexy probably isn’t worthwhile, even if you regularly redeem points for more than 1.75 cents each. If you’re only looking to earn Aeroplan points, there are plenty of cheaper ways to do so in Canada.
The more relevant use case is for someone already close to the next Air Canada status level. If routing your mortgage payments through Chexy would push you across an SQC threshold and you’ll make use of the additional benefits, the extra cost may be justified.
Ultimately, you’ll need to run the numbers based on your own situation and decide whether a steady stream of Aeroplan points and additional SQC is worth the processing fee.
Jeff Jamieson
Latest posts by Jeff Jamieson (see all)
- Chexy Mortgages: Earn Aeroplan Points & Elite Status on Your Mortgage - Nov 18, 2026
- Review: W Shanghai – The Bund - Oct 28, 2026
- Review: JW Marriott Hotel Kuala Lumpur - Oct 21, 2026
- Review: W Macau – Studio City - Oct 14, 2026
- Review: Singapore Airlines First Class Suites (A380) - Sep 30, 2026